Ownership
A share is a piece of a business we intend to own for years, not a price that moves up and down on a screen. We ask what a company will be worth in three to five years, not where its share price will be in three to five weeks.
We do not spread our capital thinly across a little of everything. When our work is done, we build concentrated positions. If a company fails even one of our criteria, we do not buy a single share.
We answer to no benchmark, no bank and no product shelf. Our decisions follow our own research, not the mood of the market or the weights of an index, and we go wherever the opportunity is greatest.
The founding partners invest their own capital alongside our partners, on identical terms. We succeed only when our partners do, and we measure ourselves by the same result.
We own companies over a horizon of several years, while the average holding period in public markets is now measured in months. Time is the one advantage most investors have given away.
Every position is built on extensive fundamental research, carried out as though we were buying the whole company. We know what a business is worth before we buy it, and we buy only at a price that leaves a clear margin of safety.
This is where the tradition of value investing meets the meaning of our name. In Greek mythology, Creon was the regent who took charge of Thebes when the city was in deep crisis, bringing structure, decisive leadership and recovery. Creon carries the role of the steadfast regent into today’s markets. We identify the companies that are removing inefficiencies, restructuring their foundations and building a lasting structure for the future, and we stand beside them as patient owners. We look beyond the crisis, to the company that emerges from it.
A strong balance sheet and enough liquidity to survive until our thesis plays out, meet every obligation and avoid forced dilution or distress.
Leaders with skin in the game, a strong say-do ratio and a shareholder-friendly record of capital allocation. We back the person as much as the business.
Strong brands or structural positions built over long operating histories and proven through cycles, protecting margins and pricing power.
A clear, identifiable path to unlocking value through concrete business change, not valuation alone: a turnaround plan, new leadership, cost discipline, asset sales or an active owner.
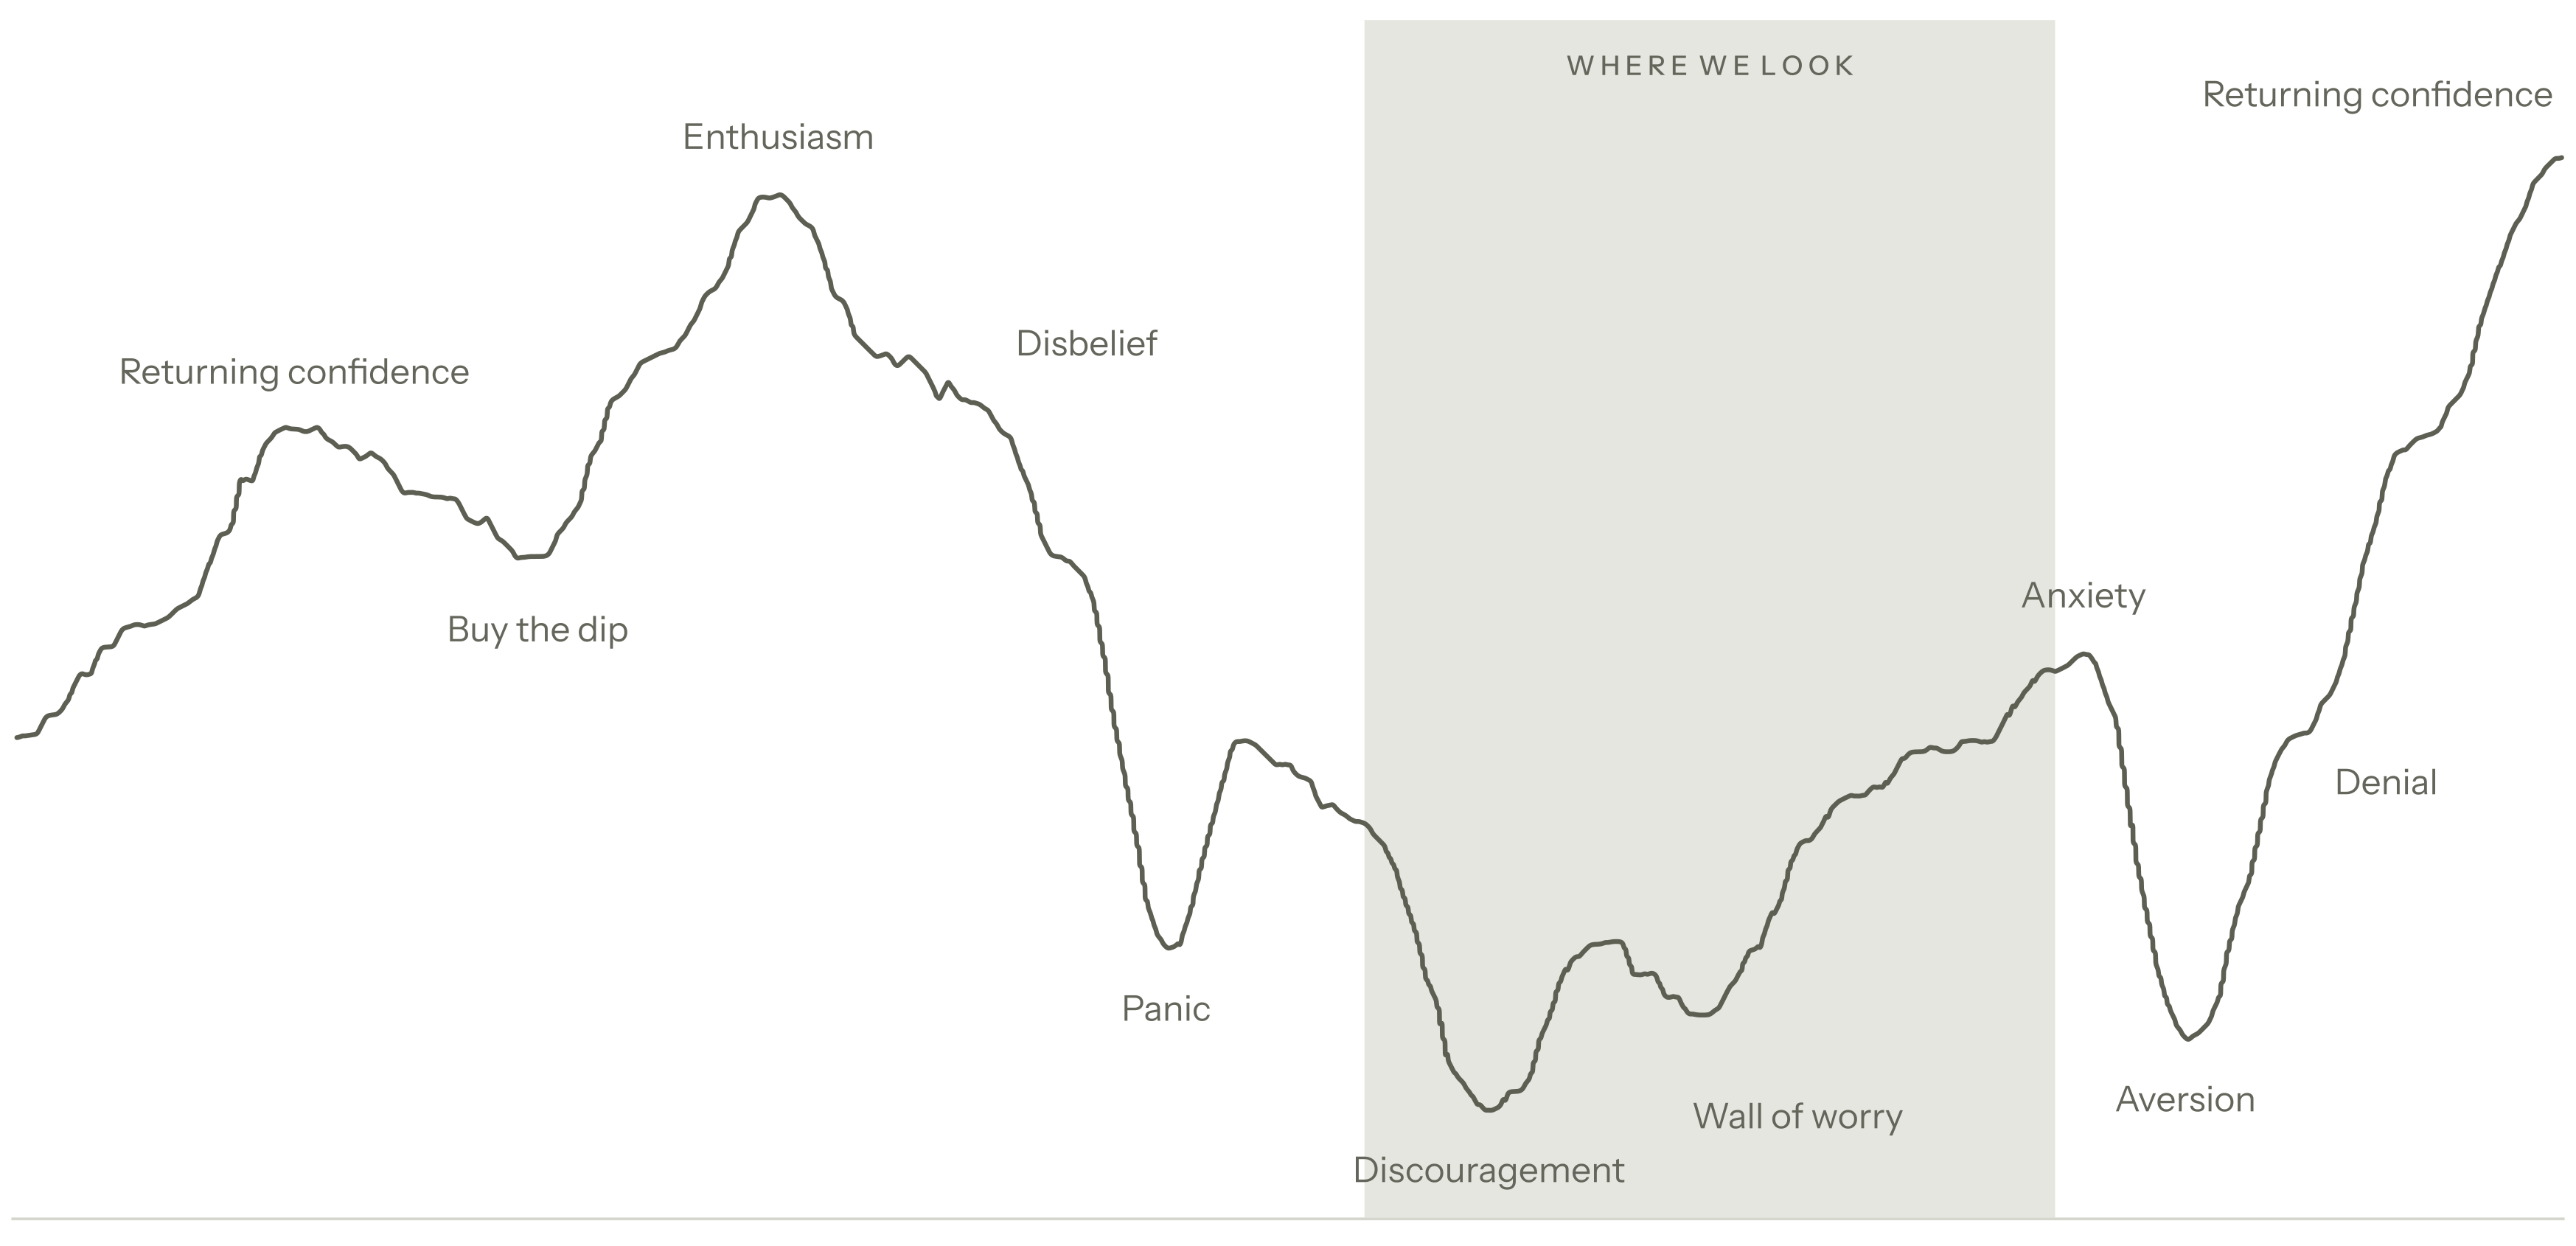
Justin Mamis described how investor sentiment moves in a recurring cycle. Prices fall furthest in panic and discouragement, often while the business itself is already quietly improving. The recovery then climbs a wall of worry: every rise is met with anxiety, aversion and denial before confidence returns. We look for good-quality businesses in that stretch, when they are least popular, and own them through the wall of worry. We do not try to time the turn.